Life insurance is a promise that the mortgage gets paid when you cannot pay it.
We are an independent broker. We look across the whole market, explain the two or three policies that actually fit, and get paid by the insurer rather than by you.
Most people need twenty minutes on the phone and one honest conversation. If you already have cover through work and it is enough, we will tell you that and you will never hear from us again.
What we arrange
- Level term
- A fixed amount for a fixed number of years. The simplest and usually the cheapest. Suits families with a mortgage.
- Decreasing term
- Cover falls in step with a repayment mortgage, so you pay for what you owe rather than what you borrowed.
- Family income benefit
- Pays a monthly income to your family instead of one lump sum. Easier to live on, harder to mishandle.
- Critical illness
- Pays out on diagnosis of a listed condition. Costs more and the wording matters more. Worth it if you are self employed with no sick pay.
What it costs
| Age and status | Cover | Term | Typical premium |
|---|---|---|---|
| 30, non smoker | 250,000 GBP | 25 years | 9 GBP a month |
| 35, non smoker | 300,000 GBP | 25 years | 14 GBP a month |
| 40, non smoker | 300,000 GBP | 20 years | 21 GBP a month |
| 45, smoker | 200,000 GBP | 15 years | 46 GBP a month |
These are real quotes from last month, not illustrations. Premiums move with age, health, smoking, weight and occupation. A declined application elsewhere does not mean you are uninsurable, it usually means the wrong insurer was asked.
How we work
- 01The call. Twenty minutes. What you owe, who depends on you, and what you already have through work.
- 02The research. We check the whole market and come back with two or three options, with the reasons, in writing.
- 03The application. We fill it in with you. Answer the medical questions honestly, including the awkward ones. A refused claim usually starts here.
- 04The review. Every two years, or whenever your mortgage, job or family changes.
Why a broker
Read the policy wording rather than the summary. Ask insurers about your specific condition before you apply. Handle the medical follow up. Help your family claim, years later, when we have no commercial reason left to care.
Nothing. The insurer pays us a commission and you pay the same premium you would pay going direct. If anyone tells you a broker costs extra, they are selling you something else.
The people
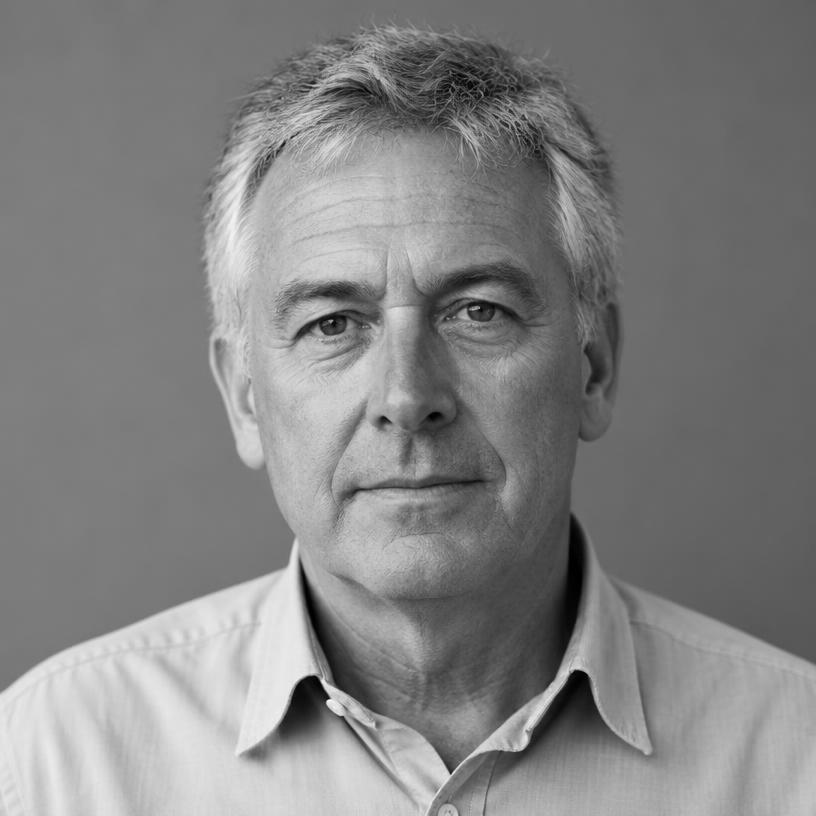 Alan Thornbury. 31 years in protection. Will talk you out of cover you do not need, which is why half our enquiries come from people he previously turned away.
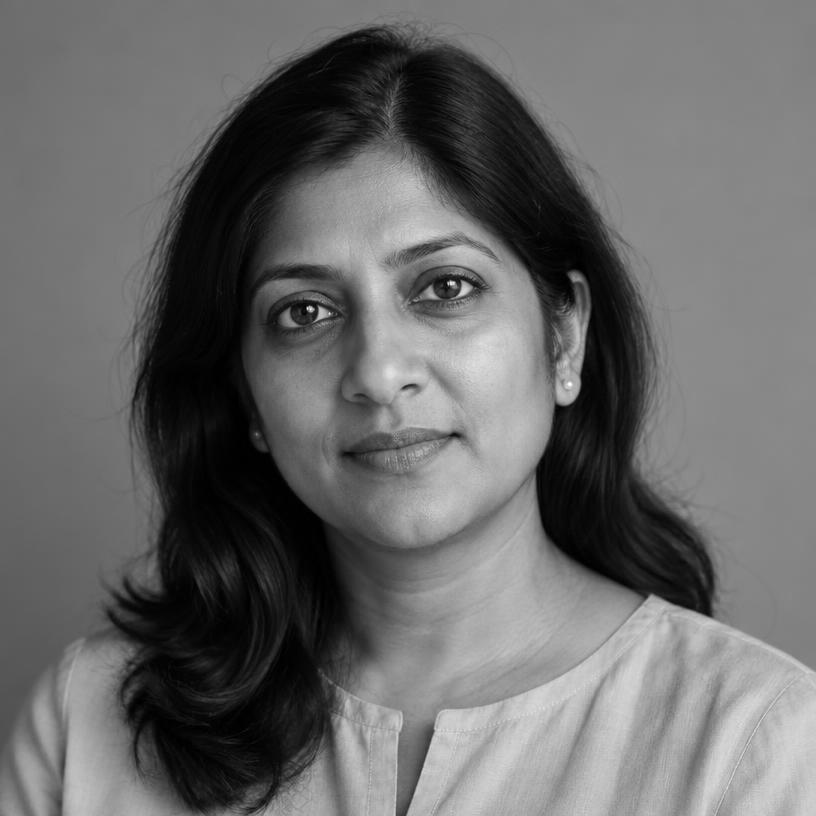 Priya Reed. 18 years, ten of them in underwriting, which is why she knows what gets declined before the application goes in.